Author: Karl Muth JD, MBA, MPhil, PhD
Council Member, Council on Global Competition and Innovation
Over a decade ago, Peter Thiel and his Silicon Valley colleagues coined a term for a particularly troublesome area of investment: ITAATYA (“it-TAT-yuh” was the pronunciation). The acronym stands for “ideas that are always ten years away.” Any venture investor who’s looked seriously at these technologies can rattle off ten additional categories without trying particularly hard; they seem like near-inevitabilities and yet billions have been spent (and lost) chasing these ethereal, conceptual dreams. And it’s because they are dreams or categories rather than concrete inventions, it is hard to invest in “an idea” rather than a technology. Some notable examples include: durable room-temperature superconductors, fusion reactors with sustained stability, continuous state quantum computers, widely-adopted augmented reality, etc. On this list of “conceptually great, but not today” until recently was not just nuclear fusion, but reasonable nuclear regulation.
Nuclear sites themselves were capital intensive, essentially uninsurable, and commercially unattractive–all three being at least in part the product of overregulation filled with impossible-to-satisfy compliance regimes. To understand why the moment is right for nuclear investment now, one must spend a moment to appreciate just how bleak things were for nuclear energy in “the bad old days.”
Until recently, private sector actors (including privately-funded investment vehicles) with the government as their only customers quickly became either proxies for government departments or lightning rods for lawsuits. See, e.g., ComEd v. Ill. Comm. Commission, 775 N.E.2d 113 (Ill. App. 2d 2002) (Kapala, J.) (bizarre and labyrinthine litigation surrounding the decommissioning of a ComEd/Exelon-managed nuclear reactor site in Illinois). Meanwhile, private sector actors trying to innovate or transform around nuclear energy operations were often unfairly critiqued as either engaging in unsafe cost-cutting or exploitative utility pricing. These accusations were not only easily-thrown, they were practically templated in public statutes in many cases. See, e.g., 220 Ill. Comp. Stat. 5/8-508.1(a)(1) (“the series of activities undertaken at the time a nuclear power plant is permanently retired from service to ensure that the final entombment, decontamination, dismantlement, removal and disposal of the plant … to ensure that such final disposition does not pose any threat to the public health and safety” … is compliance with a standard that nothing having to do with shutting down a nuclear reactor site pose any threat at all to the public even possible?).
The Nuclear Energy Innovation and Modernization Act (NEIMA), also known as S-512, mandates the Nuclear Regulatory Commission (NRC) to develop a modernized, technology-inclusive licensing framework for advanced nuclear reactors, and the Accelerating Deployment of Versatile, Advanced Nuclear for Clean Energy (ADVANCE) Act further supports the NRC’s efforts. Though NEIMA passed in 2019, it did so without the multi-billion-dollar appropriations commitments many advocates insisted were needed to truly accelerate the development of the next generation of indigenous zero-carbon, strategically-important technology to enhance American energy security. That money arrived later, in the $3.2B and growing commitment Congress has made to nuclear technology, along with a commitment in the Energy Act of 2020 to develop at least two new made-in-America reactor technologies by 2027. The Inflation Reduction Act also included credits and incentives for the development of advanced reactor designs.
Today, thanks in part to this legislative and executive support for the only zero-carbon, megawatt-base-load technology humans have ever invented, one sees more innovation than ever in recent memory four key nuclear areas (the “four Ms,” discussed below in detail); this presents a fantastic opportunity to the U.S. and its allies–and to investors interested in energy security, as well. Enthusiasm about reliable, affordable base load power in the U.S., European realization that wind and solar may not be real base load solutions, and an improving nuclear-oriented political climate in post-Fukushima Asia are ingredients for international adoption among our allies.
National security investments have been linked to nuclear investments in the U.S. since the dawn of the U.S. nuclear energy program (and DARPA’s investment in Project Orion and similar efforts with private-sector partners) and today firms like General Atomics continue this tradition by deploying a blend of money raised in civilian capital markets and DoD and DoE funds solicited through federal procurement mechanisms. This is a time of U.S. opportunity and advantage in this area, with investors from Bill Gates (small site nuclear) to General Dynamics (nuclear maritime powertrains) backing new domestic ideas for reactor design and implementation and with energy security and energy independence both becoming popular phrases on Capitol Hill.
It is worth briefly examining what’s happening now in four key areas (the “four Ms”) to show reasonably-regulated nuclear fission power technologies may not be ITAATYA: 1) materials, 2) miniaturization, 3) mining, and 4) modernization, in each section, mentioning a few key players, locales, case studies, or ideas.
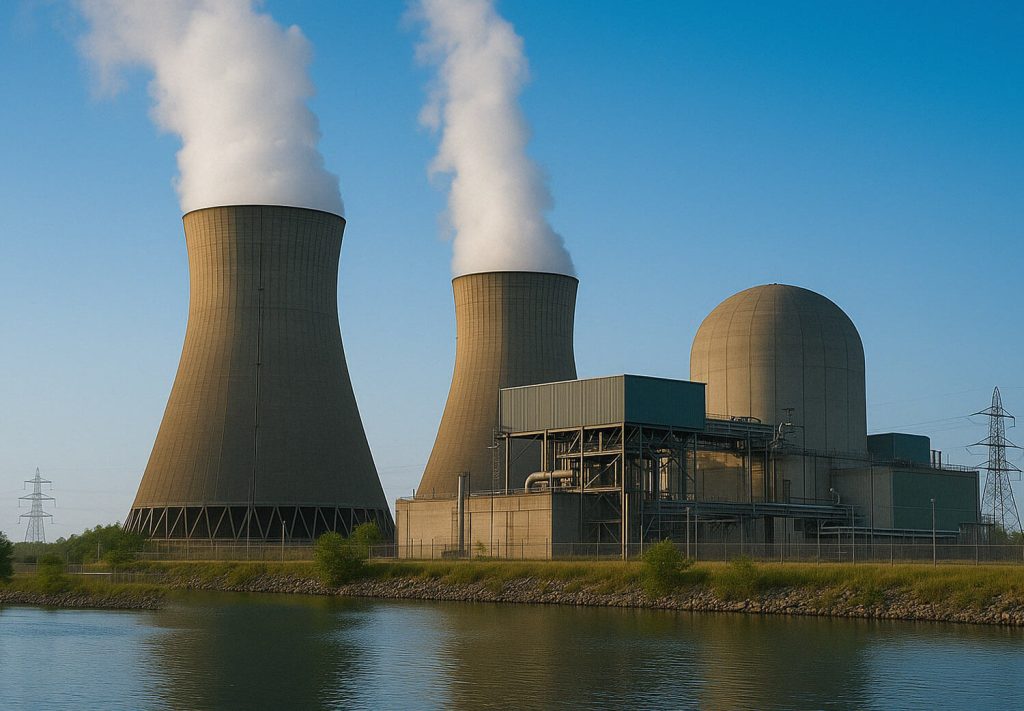
In materials, we see many of the same materials that are of interest in hypersonic missiles or orbital re-entry appearing in a static nuclear power production environment: shielding and shedding the heat inevitably generated by small-site reactors presents similar challenges. Fires, resulting from inadequate cooling/shielding designs or cooling system failures, are a feature of several well-known nuclear disasters: Chernobyl and Windscale both involved convective fires that massively amplified the amount of radioactive material released. Startups like INBRAIN, which focuses on the thermal transference and radiation shielding properties of graphene in small reactors, and C-Crete, which researches exotic cements with interesting thermal and radiation-shielding properties, are examples of interesting ventures in this space. The big story, perhaps the only story, in miniaturization is the small modular reactor. Small modular reactors (SMRs), of which there are several designs (though the small light water reactor, LWR, sodium-cooled fast reactor, and high-temperature gas-cooled reactor are three leading designs), have made the concept of a shipping-container-sized reactor providing on-site reliable power (“reactor in a box”) reality. While novel designs are appealing and the topic of much research, regulators’ familiarity with LWR designs and incremental (rather than radical) design improvements by firms like NuScale have increased the acceptance of these designs. Meanwhile, the big player in miniaturized sodium-cooled technology is Bill Gates’s TerraPower while startups like X-Energy and Blykalla are researching small gas-cooled and metal-cooled reactors, respectively. A variety of scenarios, from a rural datacenter where a reliable 200-300 megawatt base load is needed to a military installation where energy-based weapons are the norm, would justify the installation of a small modular reactor unit. The “reactor in a box” designs generate no hazardous waste to be carted away, are essentially “plug-in” devices, and include the electronics needed for basic local draw management and fault diagnosis. The market size for these safe, small, versatile nuclear power sources is vast and growing.
Mining is a resource discovery problem less so than a resource exploitation problem. Anouk Rigterink demonstrated that we have not only an empirical understanding, but robust predictive models, of where valuable resources will occur, even when they are hidden in areas we cannot yet empirically explore. See generally Anouk Rigterink, Diamonds…, Journal of Conflict Resolution 64(1):90–126 (2020) (discussing diamond deposit locations and predictive value in anticipating and evaluating related economic and political issues). Today, we enjoy a relatively comprehensive understanding of both the prevalence and location of uranium, but much of what is known (or predicted) to exist was not accessible until recently. Petra, a startup using plasma-based drilling to reach resources encased in the hardest rocks, such as legacy granite seams, offers super deep and precise drilling to reach previously-elusive deposits. Other firms to watch include Corvus Energy, which is better-known for its battery research but is also involved in drilling technology development, and Deep Reach Technology, which is developing multi-axis precision discovery drilling tools. Difficult environments like the Colorado plateau (which stretches into the “four corners” area of the southwest U.S.) and the Australian outback contain substantial amounts of nuclear material and advanced exploration techniques will be required to access these resources.
Finally, modernization is a real area of innovation. Nuclear modernization, and specifically the repurposing or upgrading of already-established nuclear sites for more modern purposes, is not a new idea. In fact, General Atomics (today best known as the manufacturer of the MQ-9 Reaper drone, every bad guy’s least favorite silhouette to see overhead) began its journey with two potentially-symbiotic projects: the TRIGA research reactor and the San Diego Supercomputer Center; its leaders, including Freeman Dyson, hypothesized that someday ultrafast computing centers would need moderate nuclear reactor base load power sources. Today, Microsoft is doing what Dyson thought of doing over fifty years ago: feeding power-hungry AI data centers with nuclear power by re-activating the dormant Three Mile Island facility best-known as the site of a nuclear plant incident in 1979. The other high-profile “reboot” modernization of an existing nuclear facility is the Palisades site in Michigan (shut down in 2022, being restarted by Holtec), though Alphabet, Amazon, and Meta are all rumored to be looking at old sites to power their ambitious (and power-demanding) plans for AI infrastructure. By localizing power generation, these firms seek to increase server uptime, de-risk service provision, and segregate business risk from infrastructure concerns like macrogrid resiliency or political concerns like local utility cooperation.
In no period in history have we enjoyed as obvious and consistent alignment of private investment, domestic government policy, defense research initiatives (including but not only at DARPA, with Project Pele), and the interests of U.S. allies around materials, miniaturization, mining, and modernization in the nuclear space. This is an area of technology where U.S. innovation can lead, encourage collaboration from allies, and enhance the distance between our capabilities and those of our adversaries. In the process, there is a multitude of opportunities to harvest important learnings, develop application-specific manufacturing, and discover important differentiating materials. Specifically, investment in a decentralized nuclear future where small civilian sites, substantial datacenter locations, remote military installations, and even commercial maritime assets are nuclear-powered seems it’s no longer ten years away, though that may well be an appropriate investment horizon for some investments made in 2025 to bear fruit.
The views and opinions expressed in this newsletter are solely those of the individual contributors of the Council on Global Competition and Innovation, Inc. (“CGCI”) and are not the views of CGCI or its affiliates.
Certain information included herein has been sourced from third parties, including external organizations or entities mentioned in this publication. While such information is believed to be reliable, CGCI has not independently verified its accuracy or completeness and makes no representations or warranties regarding its reliability or suitability for any specific purpose.
This newsletter is provided for informational purposes only and does not constitute legal, financial, investment, or professional advice. Readers should consult their own advisors before making decisions based on the content herein. Any references to specific entities, securities, or digital assets are for illustrative purposes only and do not constitute endorsements or recommendations.
This content is not intended to solicit investment or participation in any financial products or services. Past performance mentioned, if any, is not indicative of future results. CGCI disclaims any liability for actions taken based on this information.
Charts and graphs are illustrative and should not be relied upon for decision-making purposes. Any projections, estimates, forecasts, targets, prospects, and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. All content reflects information available as of the date of publication.
For further details, please refer to our Terms of Use policy at https://www.cgci.org/terms-of-use